Investor Demand is Not the Problem, Says UNEP FI Head of Nature
Once viewed as a secondary issue to climate change, nature risk is becoming a more prominent concern for the financial sector. According to a recent survey by the UN Environment Programme Finance Initiative (UNEP FI) – whose 385 member banks represent about half of global banking assets – major global institutions and European lenders across the board now rank nature higher than climate on their list of priorities.
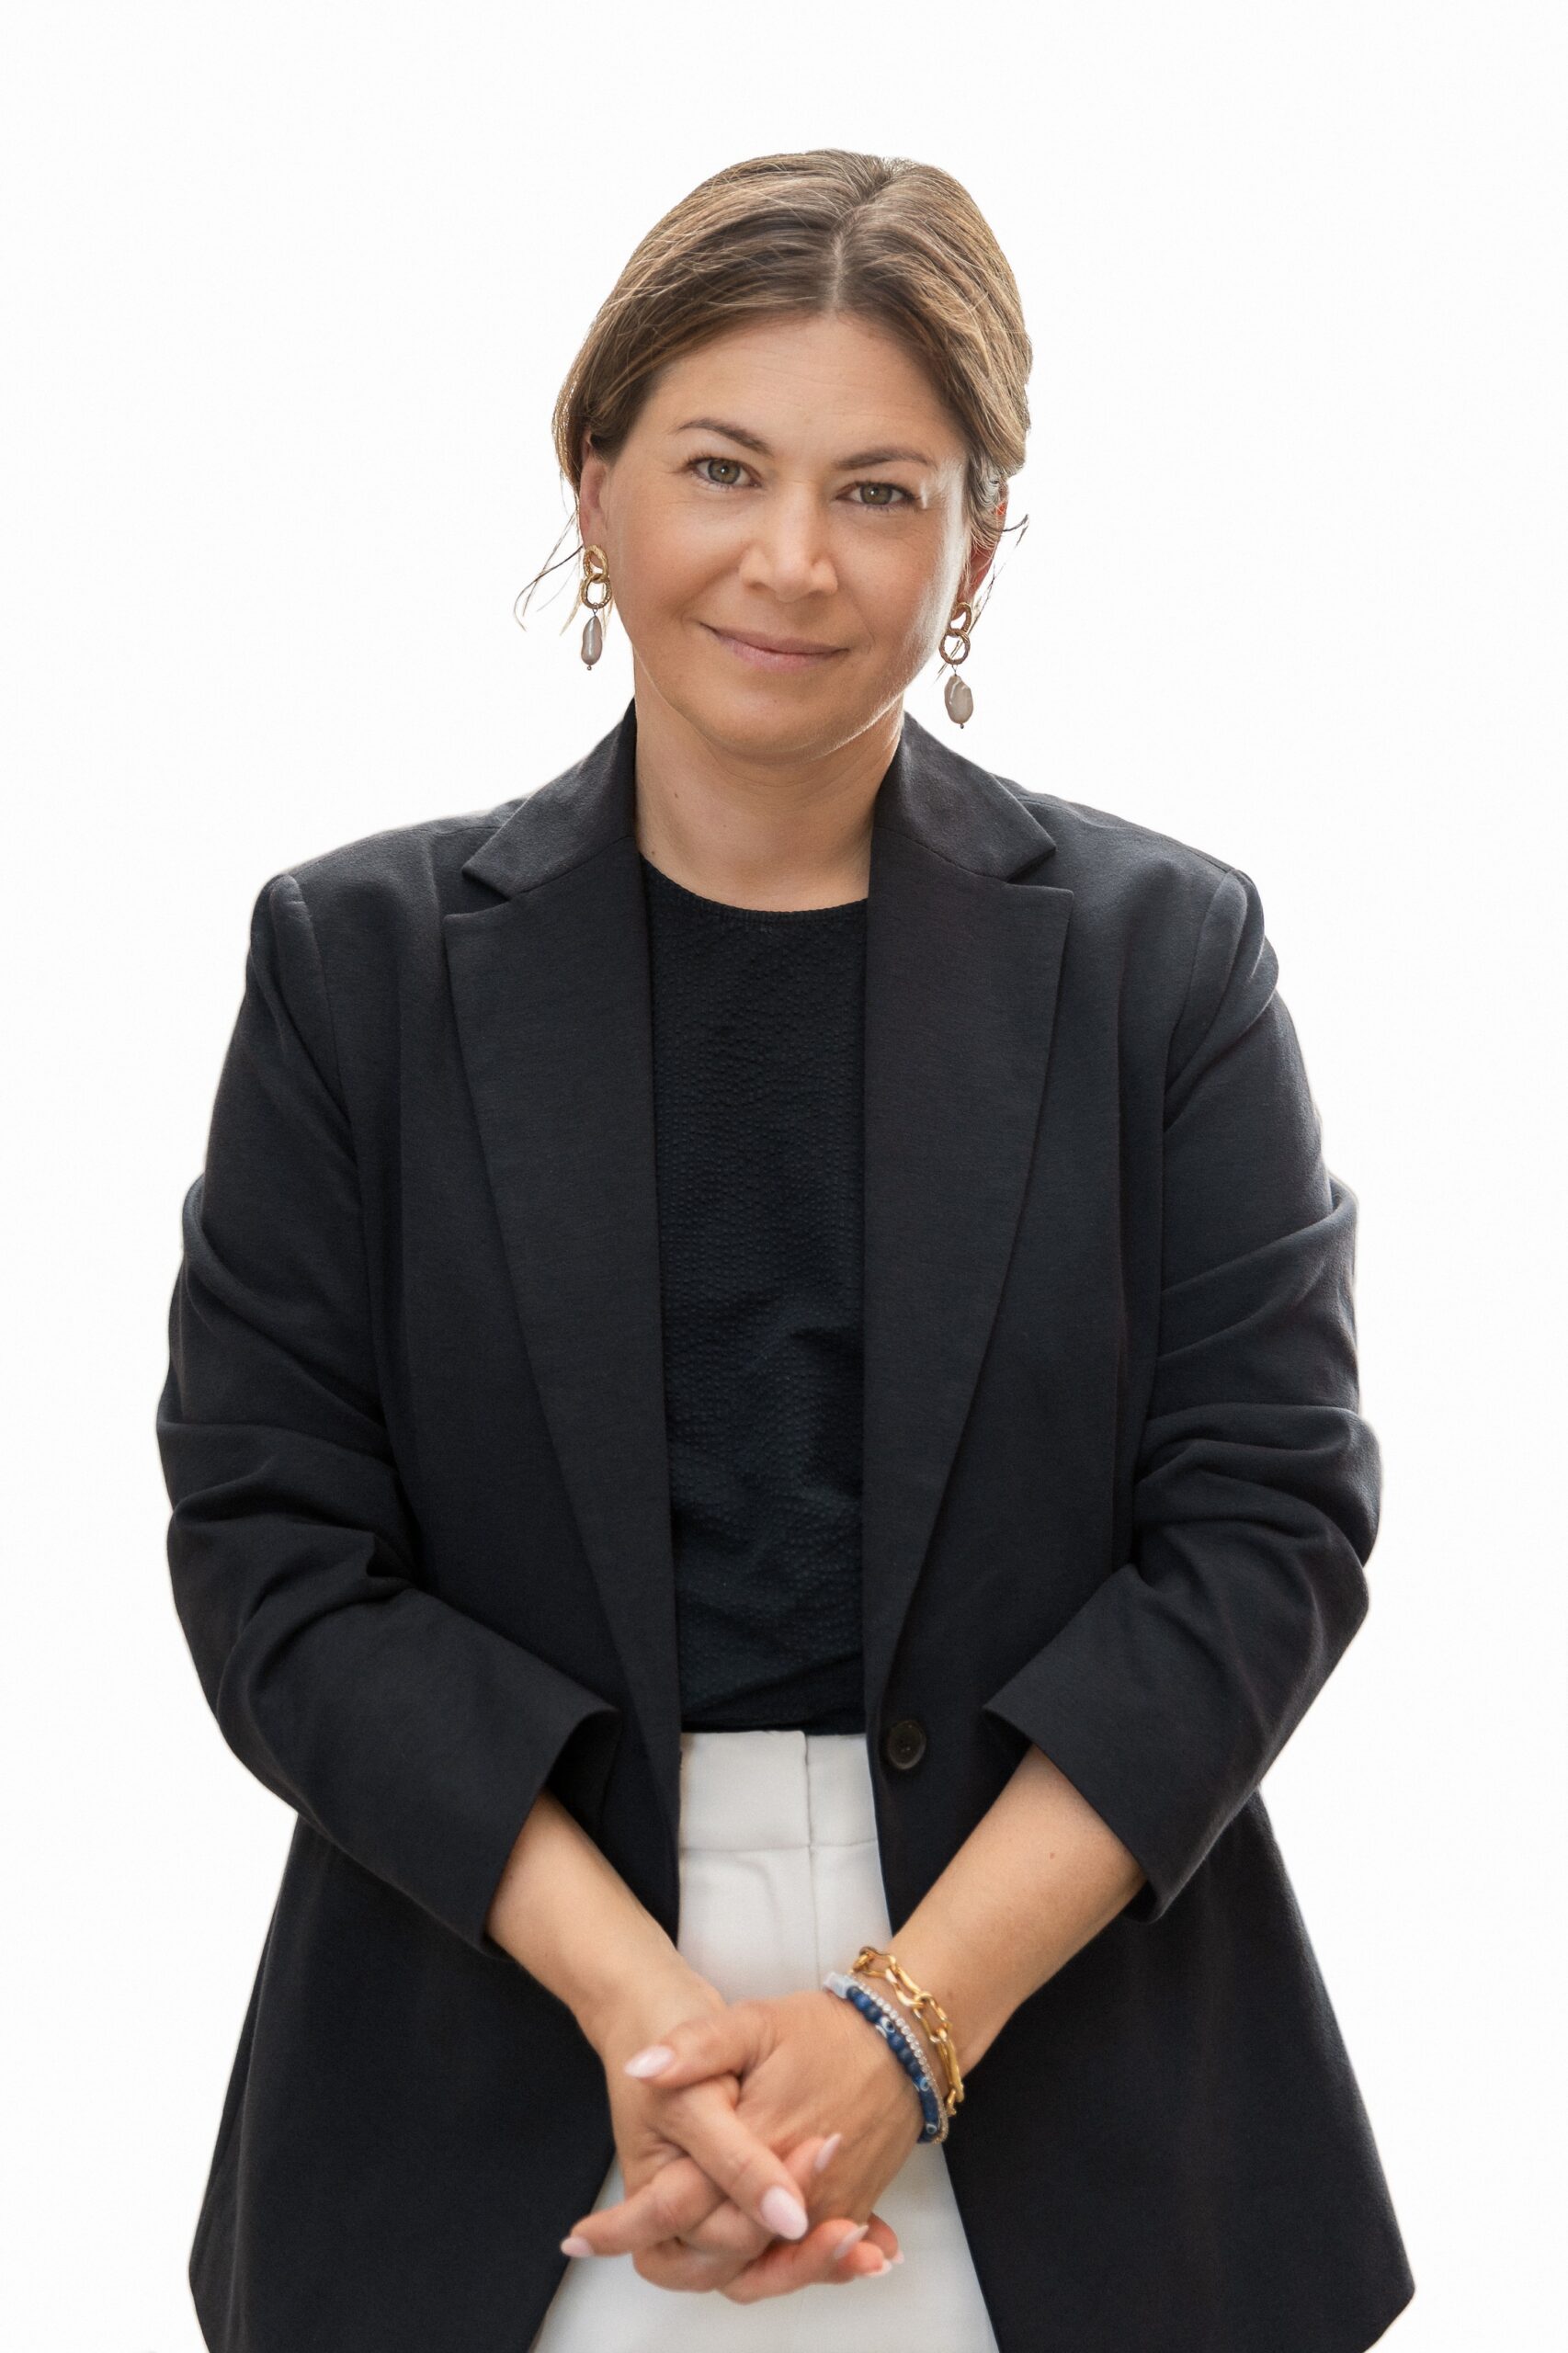
Jessica Smith is Head of Nature at the UN Environment Programme Finance Initiative, where she leads work on integrating nature-related risks and opportunities into banking, insurance and investment. She joined UNEP FI in 2020 and played a key role in establishing the Taskforce on Nature-related Financial Disclosures, a voluntary global framework that helps companies and financial institutions assess, disclose and manage their dependencies, risks and opportunities related to nature.
In this interview with OPIS Biodiversity Markets editor Nia Simeonova, Smith explains why nature is rising up banks’ agendas and what needs to change to channel more private capital into restoration, ahead of COP17 in Armenia later this month.
OPIS: Is this the first time you’ve noticed large banks prioritizing nature over climate?
 Smith: Nature has been steadily rising up our members’ agenda since the Kunming-Montreal Global Biodiversity Framework set clear expectations of the finance sector [in 2022]. Climate has normally dominated their field of view, yet increasingly members see the two meeting in food security, energy, adaptation, resilience and freshwater risk. It’s also a source of encouragement that many bankable Nature-based Solutions are emerging.
Increasingly they see the business case shape supply chains and markets. And investors have taken notice. A paper by Kalhoro and Kyaw found that banks actively managing biodiversity risks saw their share prices rise around key UN nature negotiations.
OPIS: What are the biggest hurdles for banks to engage in nature restoration more actively?
Smith: Many restoration and conservation projects are small, generate revenue slowly and carry risks that banks find hard to identify and price, from land tenure to uncertain outcome verification. Transaction costs also remain high relative to deal size. Yet, innovation is racing ahead. I find it exciting how many financial solutions are coming from Africa.
This year – in quick succession – three African transactions set new benchmarks for nature in capital markets. The Cape Water Performance-Based Bond (around $132 million), issued by FirstRand/Rand Merchant Bank, is the first bond from a commercial bank globally to link variable investor yields to verified ecological restoration, in this case watershed restoration. It shows natural capital delivering ecological infrastructure at a fraction of the cost of grey alternatives such as desalination.
The Spekboom Restoration Outcome Bond ($120 million), a triple-A rated World Bank outcome bond maturing in 2040, offers full principal protection and a fixed coupon while unlocking $25 million in private capital for 50,000 hectares of native restoration, while creating livelihood opportunities in a historically disadvantaged part of the country.
Ecobank’s $450 million Sustainable Agriculture & Natural Capital Bond is the world’s first ICMA-designated Nature Bond from a commercial bank, financing sustainable primary production, agri-processing, and water supply and sanitation across 24 markets in Ecobank’s footprint.
Orders exceeded $1.36 billion, 3.9 times the original $350 million target, allowing Ecobank to upsize by $100 million and tighten pricing by 50 basis points from initial guidance, which the bank describes as a “greenium”. Investors were, in effect, willing to accept a lower return to support nature, smallholder agriculture and freshwater.
This shows that investor demand is not the problem. The core challenge is building the plumbing between capital markets and local restoration outcomes, and trusted intermediaries are essential to that. We also place a big focus on how private finance can play more of a role valuing the knowledge of and supporting the leadership of indigenous peoples, smallholders, women and others who are nature’s front-line stewards.
OPIS: What role can biodiversity credits play in nature restoration? Have you noticed more interest?
Smith: UNEP’s latest State of Finance for Nature 2026 report finds that credit schemes, including offsets, remain the largest share of private finance directed to nature. Several countries already operate schemes. Around 19 are actively developing nature credit markets and the EU has consulted more than 1,200 experts on nature credits, so we are seeing more investor interest.
England’s Biodiversity Net Gain has been an example to watch. Net gain of biodiversity has been mandatory for major developments since February 2024, and for smaller developments since April 2024. Developers must deliver a 10% gain measured with a statutory metric, secured for at least 30 years. Where they cannot achieve it on site, they buy off-site units from habitat banks registered on the government’s Biodiversity Gain Sites Register. Natural England’s statutory credits, priced from roughly £42,000 to £650,000 ($55,000 to $857,000) each, sit above the market as a deliberately expensive last resort. Industry estimates put the market at around £93 million in 2026, up from about £33 million in 2025, with more than 300 registered gain sites.
Environment Bank is the clearest case of institutional capital entering the space: it operates England’s largest network of habitat banks, and the asset manager Gresham House launched a dedicated biodiversity strategy to invest in those habitat banks.
With the Green Finance Institute and UNDP, through the Revenues for Nature project, we will launch a new report at COP17. Entitled “Making Compensatory Conservation Investable: What Institutional Investors Need to Invest in Market-based Compensatory Conservation Schemes”, it will explore this further.
OPIS: What do you expect at COP17 and what is UNEP FI hoping to achieve?
Smith: Finance will be central in the debate on progress. We will publish a “report card” on how the financial system has performed for nature between the Cali COP [in 2024] and this one. There is indeed a growing trend of finance flowing for nature, but the data has not caught up. Our own UNEP State of Finance for Nature 2026 data lacks some newer asset classes and is benchmarked to 2023; it needs to become more comprehensive and timely to be decision-relevant for everyone working to meet the Kunming Montreal Global Biodiversity Framework (KMGBF) targets by 2030.
While Target 19 explicitly calls for leveraging private finance through instruments such as green bonds, payments for ecosystem services and biodiversity credits, yet we struggle to fully measure progress. Very few parties to CBD reported private finance under headline indicator D3, which measures the total amount of private funding directed toward the conservation and sustainable use of biodiversity and ecosystems.
We believe this is at least partly a reporting gap rather than a gap in market activity. Equally, Target 18 on reforming harmful incentives means we need a clear view of the flows that damage nature, not just those that support it. We’ve modelled this in the SFN but still needs to be complemented by new data on transition finance for which data sets don’t yet exist.
One of our priorities at COP17 is to bring financial institutions, governments and funders together to build momentum for a common voluntary reporting template for nature-related private finance. Developed with financial institutions and aligned with the D3 indicator in the GBF monitoring framework, it could serve to provide country-level data on finance going towards conservation, restoration and enabling conditions.
As an input to this, we are working with the Finance for Biodiversity Foundation, with GEF support and WWF involvement, on high integrity definitions of transition finance for different asset classes, building on our earlier joint Finance for Nature Positive discussion paper.